Compliance software for regulated finance

Know who your customer is. See what their money does.

Compliance4B gives banks, e-money and payment institutions one place to onboard clients, monitor every payment, investigate alerts and keep their control environment ready for the examiner.

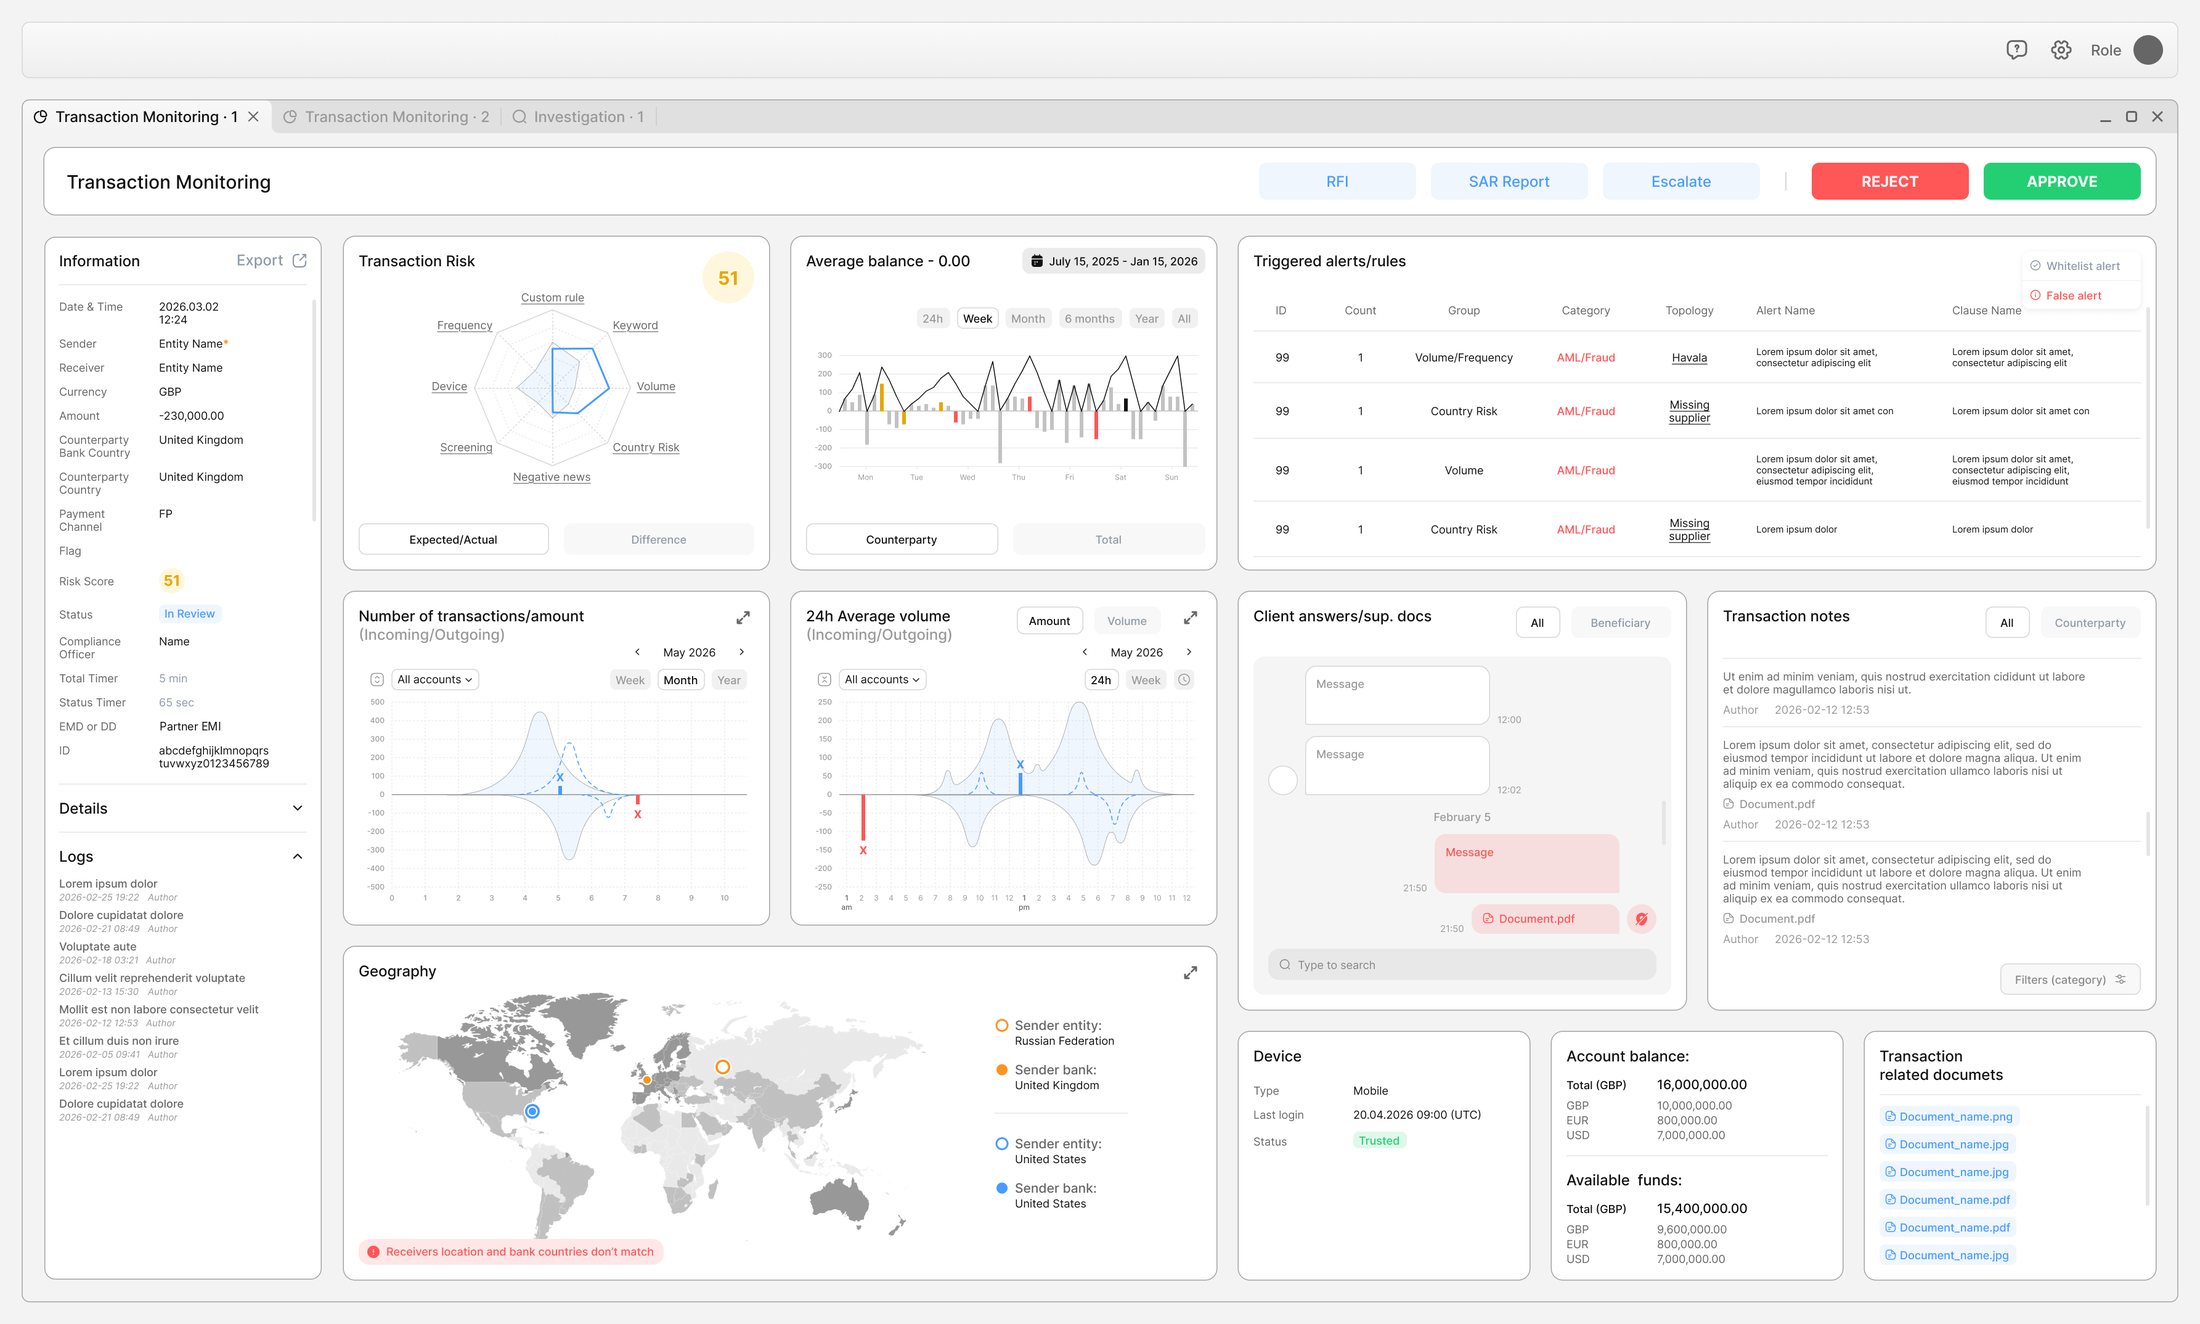
Compliance4B case review screen for a £230,000 outgoing payment, showing a transaction risk radar, triggered rules, client answers, a geography check and approve or reject controls
Risk score 51Volume and country risk drove this one. The radar shows why.
Decision barRFI, SAR, escalate, reject or approve, each logged with a reason.
Geography checkReceiver location and bank country don't match.
3 suitesOnboarding, financial crime and GRC, sold separately or together
1 recordEvery suite reads the same customer, score and audit trail
4 regimesContent prepared for US, UK, EU and UAE requirements
3 ways to runMulti-tenant SaaS, private cloud or on-premise

Product tour

Five screens your compliance team would use every day.

Pick a screen. Click a numbered marker, or an item in the list, to see what each part does.

One alert, start to finish

How a £230,000 payment gets reviewed.

This is the case on the screen above. The times are illustrative. The steps are how the product works.

09:12

Payment scored at 51

A faster payment to a UK counterparty trips a volume rule and a country risk rule. The case opens as Waiting for review with both timers running.

09:31

Analyst picks it up

The case screen shows the radar, the rules that fired and the customer's normal 24-hour volume. The receiver's location does not match their bank's country.

09:38

RFI sent from the case

The analyst asks for the invoice and the supplier contract. The status moves to RFI sent and the customer gets a secure link.

Next day

Customer answers in the thread

Two documents arrive in the client answers panel, timestamped against the case. The analyst adds a note for the reviewer.

Next day

Decision recorded

Approved with a reason code, or escalated to the MLRO with the full file. If a SAR is needed, the report draws on the same case data.

After

The record keeps working

The outcome updates the customer's risk score, and the case becomes evidence for the monitoring control in Govern.

Why Compliance4B

Made by a team that has sat across the table from a regulator.

Shaped by real supervision

The screens came out of running onboarding, monitoring and audits inside a licensed payments business. Each field exists because someone needed it in a review.

Compliance owns the settings

Your team edits questionnaires, scoring weights, rules and approval routes. Each change is versioned and approved, without a ticket to engineering.

Every number explains itself

Scores show their factors. Alerts show the rule and the data. AI suggestions show the clause they came from. Analysts and examiners can check all of it.

Fits mid-sized firms

Enterprise suites are priced and staffed for large banks. Compliance4B is sized for institutions whose compliance team fits around one table.

See it with your own scenarios.

Home / Monitor

Compliance4B Monitor

Every payment scored. Every alert closed with a reason.

Monitor covers anti-money laundering, counter-terrorist financing and fraud on one engine. Analysts work from a single queue, investigate on one screen, ask the customer for evidence and record a decision the examiner can follow.

Alert queue

Start the day knowing exactly what is waiting.

The queue lists every screened transaction with its score, flag, status and owner. Status chips double as filters and show the backlog behind each one.

Case review

Everything needed to decide, on one screen.

The payment, the reasons it scored, the customer's normal behavior, their answers and their balances. The analyst does not open another system to make the call.

Investigation

Follow the money across counterparties.

When one alert is part of a pattern, investigators switch to the graph. It shows who paid whom, how much, and which flows are already suspicious or blocked. Select a period on the timeline and the graph redraws for that window.

Rule builder

Write detection logic the way your risk assessment reads.

Combine conditions on amount, velocity, counterparty, corridor, customer risk band and behavioral baseline. Backtest against past data, compare alert volumes with the live version, and promote only after a second person approves.

  • Typology library: structuring, pass-through, hawala, missing supplier, dormant reactivation, high-risk corridors
  • Thresholds by segment, product and risk band
  • Whitelisting and false-alert marking feed back into tuning
Rule TM-R-207 · version 3 draftBacktest complete
# Structuring below the reporting threshold
WHEN count(cash_deposit, 7d) >= 4
AND each(cash_deposit.amount) BETWEEN 8,000 AND 9,999
AND sum(cash_deposit, 7d) > 30,000
THEN alert(priority=P1, typology="STRUCTURING")
Lookback period90 days
Alerts, version 3 vs version 237 vs 47
ApprovalAwaiting checker

Example rule and backtest figures.

Detection coverage

Rules where you need certainty. Models where you need reach.

AML and CTF monitoring

Real-time and batch monitoring of account, card and wallet payments across CHAPS, Faster Payments, SEPA, TARGET2, SWIFT and ACH.

Fraud prevention

Checks for account takeover, authorized push payment scams and money mule behavior before funds leave, with hold and release.

Behavioral anomalies

Each customer is compared with their own history and their peer group. Alerts list the drivers, so a model hit is as explainable as a rule hit.

Payment screening

Payment parties and references screened against sanctions lists before execution, with fuzzy matching and documented whitelists.

Continuous risk scoring

Case outcomes, screening hits and behavior change the customer's risk score between reviews. A rising score can bring the review date forward.

Reporting to the FIU

SAR and STR packages built from the case narrative, parties and transactions, in the format your financial intelligence unit expects.

Case lifecycle

Clear states, timers on every one.

Waiting for reviewIn reviewRFI sentEscalated to MLROApproved · Rejected · SAR filed

SLA timers

A total timer for the case and a status timer for its current state. Managers see which cases are ageing before they breach.

Four-eyes closure

High-risk closures need a second reviewer. Analysts cannot approve their own escalations.

QA and MI

Sample closed cases for quality review. Report alert volumes, ageing and SAR conversion by rule and segment to the board.

Monitoring is only as good as the client file behind it.

Home / Onboard

Compliance4B Onboard

The whole client on one file, from first form to fifth review.

Onboard runs KYC for individuals and KYB for companies. It collects the data your policy asks for, maps ownership and control, screens every party and scores risk. When a section is incomplete, you request that exact item from the client.

Company file

A KYB record you can actually read.

On the left, the summary analysts check first: score, status, review date, ownership. On the right, the structured sections behind it. Both panes scroll, as they do in the product.

Related entities map

Ownership and control, drawn out.

Trusts, nominees and layered holding companies are where the hard KYB cases live. The map shows every party and the role that links them, with the client profile and transaction history alongside.

Individual file

Directors, shareholders and personal clients get the same depth.

Identity documents, address history, tax residency, political exposure, source of wealth and screening, with the gaps marked in red.

Risk scoring engine

Score risk the way your policy is written.

Assign scored fields to categories such as customer, geography, product and delivery channel. Choose from more than ten scoring methods, set category weights, and add minimum bands so that one decisive fact, like a PEP match, lifts the score into the right band on its own.

Method familyHow it scores
Average and maximumAverage or highest score across fields and related entities
Category averagesHighest or average per category, then averaged, with or without zero scores
Weighted categoriesWeights that add up to 100%, for example customer 30%, geography 30%, channel 20%, product 20%
Bands and overridesA triggered band or legal override adjusts the final score in proportion

Worked example: PEP = Yes sets a minimum band of High

LOW0–30
MEDIUM31–80
HIGH81–100

base score 45, band range 81–100
weight = (100 − 81) / 100 = 0.19, and 0.19 × 45 = 8.55
final score = 81 + 8.55 = 89.55, High

Feature list

What comes in the box.

ON-01

Applications and entities

Add directors, shareholders, UBOs and other related parties with their data and documents. Reuse an entity across applications instead of collecting it twice.

ON-02

Client outreach portal

Send secure requests for forms, questionnaires and documents. Corporate clients get their own login to manage their applications.

ON-03

Video KYC

Schedule and record face-to-face calls with playback, and match the face on camera to the identity document.

ON-04

Company registry lookup

Search company registries and import fields, filings and officers straight into the application.

ON-05

Screening

Sanctions, PEP, adverse media, law and regulatory enforcement, disqualified directors and more, with scheduled re-screening.

ON-06

Documents with expiry

Track every document as active, expiring or missing. Verify by hand or through automated authentication and OCR.

ON-07

Checklists and lifecycle

Onboarding and review checklists per entity type, and the statuses an application moves through.

ON-08

Risk-based reviews

Review dates follow the risk band, with manual override at application, entity or category level. Risk snapshots are kept between reviews.

ON-09

Deadlines and escalations

Deadlines and extensions on applications, and escalations routed across teams and roles.

ON-10

Programs

Configure each onboarding program's questions, required documents, scoring method and review cycle.

ON-11

Communication queues

Client messages sorted into compliance, support, operations and sales queues, with unread and overdue counts.

ON-12

Reports, roles and audit

A report designer with scheduled CSV exports, PDF client files, role-based access and a full action history.

Put the client file to work in monitoring.

Home / Govern

Compliance4B Govern

From regulator circular to tested control, with the trail kept.

Govern holds your policies, risks, controls and evidence in one system of record. When a new rule arrives, it reads the document, proposes obligations and controls, routes them for approval and schedules the evidence. When the auditor asks, the answer is already linked.

Regulatory intake

AI reads the circular. Your people decide what applies.

Upload a law, circular, guideline or MoU in English or Arabic. Govern separates mandatory obligations from guidance, cites the exact clause and page, and proposes controls with a rationale and confidence score.

No control becomes applicable until Compliance and Legal approve it, in sequence or in parallel, as your approval matrix requires. Either can send it back for more information.

DraftUnder reviewApprovedActiveEvidence awaiting reviewValidated

Interpret

Classify the document, extract obligations, keep each one tied to its clause.

Approve

Compliance and Legal approve, reject, comment or send back. Every action is logged.

Assign

The business unit owner acknowledges, challenges or reassigns. Acknowledgement makes the control active.

Validate

Evidence requests open automatically. Approved evidence is locked as a version and the control is validated.

Enterprise risk assessment

Know your material risks and how well each is controlled.

Build a three-level hierarchy from enterprise risk statements down to local registers. Score inherent risk, apply control effectiveness for residual risk, and watch key risk indicators against appetite.

  • Cyber, operational, financial crime, third-party, strategic and conduct taxonomies
  • Scoring formulas that follow your own methodology
  • Risk and control self-assessments sent to each business unit
  • Action plans ranked by residual risk

Platform structure

Five modules on one record.

ModuleWhat it holdsMain users
Enterprise structureBusiness units and departments, processes, applications and assets, facilities, data classificationAdmins, risk owners
Risk managementRisk hierarchy, inherent and residual scores, methodology, key risk indicatorsCRO, risk team, BU owners
Compliance and controlsRegulatory library and obligations, master control library, procedures, evidence, self-assessments, control testingCompliance, Legal, control owners
Issues and remediationFindings with severity, corrective and preventive actions, milestones, approved exceptions with expiryInternal audit, Compliance
Reporting and workflowNotifications, escalations, role-based dashboards, planning calendar, heat maps, traceability reportsEveryone, including the board

Audit readiness

One calendar for everything that falls due.

Policy renewals, control re-tests, evidence submissions, exception expiries and regulatory deadlines appear in one planning calendar. High-risk controls are re-tested more often. Every date change records who changed it and why.

Policy library

Owners, versions, approvals and review dates, linked to the controls each policy governs.

Map once, reuse

Map controls to ISO 27001, ISO 22301, SOC 2, DORA and local rules, then reuse the evidence.

See one regulation become owned, tested controls.

Book a demo

Home / Platform

The platform

Six shared engines under three products.

Every suite uses the same customer record, rule engine, risk engine, workflow engine and audit log. So a screening hit in Onboard raises the score Monitor uses, and a failed monitoring control opens a finding in Govern, with no integration project in between.

CORE-01

Customer record

Individuals, companies, related parties, accounts and counterparties in one graph that every suite reads.

CORE-02

Rule engine

One visual builder for detection rules, routing rules and calendar logic.

CORE-03

Risk engine

Scoring methods, category weights, bands and overrides. Every score keeps its history and its reasons.

CORE-04

Workflow engine

Role-based tasks, maker-checker, sequential or parallel approvals, SLAs, escalations and send-backs, set up by admins.

CORE-05

AI assistance

Reads regulatory documents, summarizes cases and suggests controls. It always cites its source and a person always decides.

CORE-06

Audit log

Every action, field change, comment, approval and document version, timestamped and searchable.

Integration and security

Connects to the systems you already run.

APIs and webhooks

REST APIs for onboarding, transaction ingestion, screening and case events. Webhooks send decisions back to your core banking or payments system.

Your data providers

Plug in the identity, document, company registry, sanctions and PEP providers you already have contracts with.

Microsoft 365

Keep policies and evidence in SharePoint, where staff already work. Govern tracks owners, versions and review dates on top.

Access control

Single sign-on with SAML or OpenID Connect, role-based permissions and segregation of duties enforced in the workflow.

Deployment and licensing

Run it the way your regulator expects.

Cloud SaaS

Multi-tenant

The fastest start. Annual subscription per suite, priced by active customers or users, plus usage fees for checks and screening. Hosting regions in the US, UK and EU.

Private cloud

Single-tenant

A dedicated environment in your chosen region or cloud account, for firms that need isolation, their own encryption keys or custom retention.

On-premise

Licensed install

A term license for banks that must keep data inside their own infrastructure, with implementation and support packages.

Talk to us about your architecture.

Contact the team

Home / Industries

Who we serve

Regulated financial firms, and the professionals around them.

Our customers have AML obligations, a supervisor and a small team carrying both. They operate in the US, the UK, the EU, the UAE and further afield.

Monitor · Onboard · Govern

E-money institutions

Business account onboarding, wallet and payment monitoring, safeguarding and operational resilience controls.

Monitor · Onboard · Govern

Payment institutions and money transmitters

High-volume payment monitoring, corridor risk, pre-payment fraud checks and licensing obligations in each market.

Monitor · Govern

Banks and credit unions

Explainable rules and case management alongside existing core AML systems, plus enterprise risk and control testing.

Onboard · Monitor

E-money distributors and agents

One onboarding standard across a distribution network, with the principal able to see each distributor's cases.

Onboard · Govern

Accountants and law firms

Client due diligence and periodic reviews that satisfy professional-body AML supervisors, with a file you can defend.

Onboard · Govern

Real estate and trust services

Buyer, seller and beneficial owner checks for property and company formation work in higher-risk sectors.

Regulatory coverage

Prepared for the regimes you report to.

Typologies, questionnaires and obligation libraries come prepared for each jurisdiction. Your team adapts them to your own policies.

US

United States

  • Bank Secrecy Act and USA PATRIOT Act
  • FinCEN CIP and beneficial ownership
  • SAR and CTR workflows
  • OFAC sanctions screening
UK

United Kingdom

  • Money Laundering Regulations 2017
  • FCA SYSC and JMLSG guidance
  • SARs to the NCA
  • Operational resilience
EU

European Union

  • AML Directives and AML Regulation
  • AMLA supervisory standards
  • DORA ICT risk management
  • PSD2 authentication and fraud reporting
AE

United Arab Emirates

  • Federal AML/CFT law and CBUAE standards
  • goAML STR reporting
  • Targeted financial sanctions
  • Arabic and English document intake

Working in another jurisdiction?

Tell us about it

Home / Investors

Investor overview

Compliance software built inside a regulated business.

Compliance4B is a US company. It is taking onboarding, financial crime and GRC tools first built for a licensed payments operation and offering them as a platform to regulated firms in the US, UK, EU and UAE.

Investment thesis

Why this platform, and why now.

1

The rulebook keeps growing

New AML regulations in the EU, beneficial ownership rules in the US, operational resilience in the UK and fraud reimbursement duties all land on the same small compliance teams. Examiners now ask for evidence.

2

Mid-sized firms are poorly served

Large GRC and AML suites are priced and staffed for global banks. E-money, payment and professional firms make do with spreadsheets, shared drives and three vendors that don't share data.

3

One data model is hard to copy

Onboarding data drives the risk score. The score drives monitoring. Monitoring outcomes become control evidence. Point products sit on one link of that chain.

4

Designed under supervision

The workflows were shaped by a licensed payments business going through real regulatory audits. That shortens the path to credible sales with compliance buyers.

Market position

Where Compliance4B sits.

CapabilityKYC portalsFinCrime platformsEnterprise GRCCompliance4B
KYC and KYB onboardingYesPartialNoYes
Transaction monitoring and fraudNoYesNoYes
Case management with client RFIsPartialYesNoYes
Policies, controls and evidenceNoNoYesYes
Shared customer record and scoreNoPartialNoYes
Priced for mid-sized firmsVariesRarelyRarelyYes

Typical category coverage. Individual vendors vary.

Business model

Recurring revenue from three suites.

Subscriptions

Annual SaaS fees per suite, tiered by active customers, transaction volume or users.

Usage

Per-check fees on screening, identity, document and registry lookups.

Enterprise licenses

Private cloud and on-premise term licenses for banks and larger institutions.

Services

Implementation, jurisdiction packs, policy templates and managed review support.

Go to market

Three routes to customers.

A

Direct sales

E-money institutions, payment institutions and money transmitters, where all three suites fit.

B

Audit and advisory partners

Consultants and auditors recommend the platform to the firms they advise, so findings get fixed in a system.

C

Cloud marketplaces

Listings on enterprise marketplaces, starting with Microsoft, where many buyers already keep their policies.

Growth plan and use of funds

What investment speeds up.

PHASE 1

Product team

  • Dedicated engineering and product team
  • Multi-tenant SaaS architecture
  • Each suite deployable on its own
PHASE 2

US launch

  • US hosting region
  • Independent security attestation
  • US regulatory content packs
PHASE 3

Channels

  • Audit and advisory partner program
  • Marketplace listings
  • Data provider partnerships
PHASE 4

Scale

  • Regulatory AI in more languages
  • Wider fraud models
  • More jurisdictions

Ask for the investor pack and a live walkthrough.

Home / Contact

Contact

Book a demo or start a conversation.

Reach us directly

We reply within one business day.

Sales and demos

hello@compliance4b.com

Investor relations

investors@compliance4b.com

Partners

partners@compliance4b.com

Headquarters

United States